Categorizing stablecoin yield models: CeFi, DeFi, and structured strategies
In the digital asset ecosystem, 'stablecoin staking' is an umbrella term encompassing fundamentally different financial models. Because USDT is a dollar-backed currency rather than a proof-of-stake blockchain token, returns are generated by putting capital to work across distinct institutional or market environments.
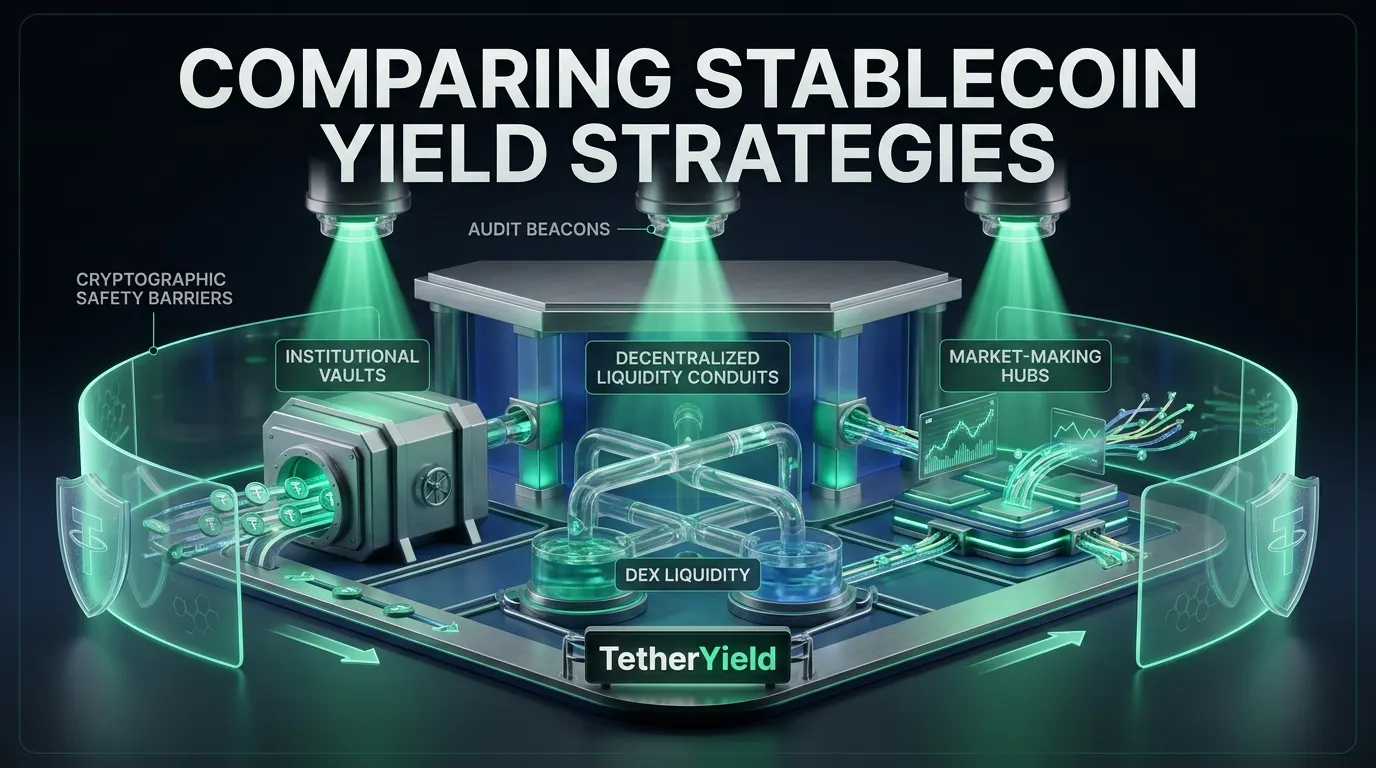
Centralized finance (CeFi) models rely on institutional lending and exchange order-book liquidity. Decentralized finance (DeFi) protocols utilize automated market makers (AMMs) and algorithmic lending pools governed by smart contracts. Structured platforms, including curated options like TetherYield, integrate market-neutral arbitrage, treasury assets, and segregated institutional custody. Knowing which model you are engaging with is the vital first step of due diligence.
- Institutional lending (CeFi): yields derived from interest paid by verified institutional borrowers.
- Decentralized pools (DeFi): returns generated through transaction swap fees and liquidity pool incentives.
- Structured yield strategies: portfolios balancing treasury-backed cash flows and delta-neutral arbitrage.
- Custody architecture: distinct operational boundaries between self-custodial contracts and institutional segregated vaults.
Red flags in high headline yields: identifying hidden leverage and promotional traps
When browsing yield products, astronomical headline percentages frequently capture retail attention. However, in institutional finance, risk and return are inseparable. A yield rate significantly higher than prevailing market baselines almost always hides asymmetric risks.
Common red flags include platforms financing returns by issuing their own hyper-inflationary reward tokens, employing unhedged directional market leverage, or enforcing opaque multi-month lockup periods where users cannot exit during market distress. If a platform cannot clearly articulate where its profits come from in simple economic terms, your principal is at risk.
- Synthetic token payouts: rewards paid in volatile secondary tokens rather than authentic, redeemable USDT.
- Temporary promotional bait: short-lived promotional subsidization that crashes once user capital is successfully locked.
- Hidden re-hypothecation: lending user deposits multiple times without transparent collateral requirements.
- Opaque corporate structures: platforms lacking verifiable company registration, executive transparency, or audit disclosures.
Distinguishing token price stability from overall product safety
A common misconception among beginner investors is assuming that because USDT is pegged to $1.00, any product holding USDT is automatically safe. While holding a stablecoin protects against the price volatility of Bitcoin or altcoins, it does not eliminate product-level operational risks.
Product safety is determined by the custody practices, protocol security, network throughput, and administrative terms of the platform holding your funds. A project could hold 100% USDT, yet fail due to smart-contract exploits, frozen withdrawal portals, or insolvent counterparty borrowers. Disciplined allocators evaluate product resilience independently from stablecoin price stability.
- Stablecoin peg resilience: monitoring underlying issuer reserve attestations and redemption mechanics.
- Platform solvency: ensuring capital is managed with isolated accounting rather than mixed company operational pools.
- Smart-contract auditing: verifying independent third-party code audits without backdoors or single-key administrator controls.
- Network transfer efficiency: factoring in confirmation times and gas fees across TRC20, ERC20, and BEP20 networks.
Essential due diligence: verifying custody, liquidity rules, and exit timelines
The difference between a stressful investment experience and a seamless one almost always comes down to liquidity terms. Two platforms offering identical annual yields can provide opposite outcomes if one allows flexible daily withdrawals while the other locks funds for 90 days with complex unbonding procedures.
Prior to funding any yield account, thoroughly examine the terms of redemption. Confirm whether daily interest is credited directly to an available balance that can be withdrawn at any time, what processing windows apply, and whether early exits incur financial penalties. Transparency regarding how and when you get your money back is the truest indicator of platform integrity.
- Commitment duration: flexible on-demand access versus rigid multi-week locked terms.
- Reward settlement cadence: daily balance crediting versus maturity-locked accumulation.
- Capital-release mechanics: explicit and automated procedures for returning principal to private wallets.
- Fee disclosure: complete transparency regarding withdrawal spreads, network gas deductions, and management costs.
A 5-step verification checklist before sending your capital
A standardized due diligence routine protects you from impulsive decisions driven by marketing hype or fear of missing out. Apply these five golden questions before allocating capital to any stablecoin strategy.
At TetherYield, operational transparency is built into our core philosophy. We provide clear plan terms, verifiable payout schedules, and complete risk documentation in our Trust Center. By conducting disciplined due diligence before funding, you ensure that your stablecoin capital works safely and compounds reliably.
- What exact economic mechanism generates the advertised yield, and who pays for it?
- Who holds cryptographic custody of my funds while the strategy is active?
- Are the yields paid in real USDT or in speculative inflationary project tokens?
- Can I withdraw my daily interest and principal flexibly, or am I locked into fixed terms?
- Have I thoroughly read the official terms of service, fee schedules, and comprehensive risk disclosures?